What happens when a home appraisal comes in low?
A low appraisal doesn’t automatically mean you’ve lost the house—or that you’re required to pay the difference. Here’s how Southern New Mexico buyers can navigate appraisal gaps and subject-to conditions.
What is a home appraisal?
When you’re financing a home, your lender generally requires an appraisal as part of the loan process. The appraiser develops an independent opinion of the property’s value using information that may include recent comparable sales, the home’s location, size, condition, features and current market activity.
The appraisal is different from your home inspection. A home inspector evaluates the property’s systems and condition for the buyer, while the appraisal is primarily concerned with the property’s value and, depending on the loan program, whether certain property requirements are met.
Ideally, the appraised value supports the purchase price and the transaction moves forward without required repairs. But sometimes the appraised value is lower than the price in your purchase agreement—or the appraisal identifies conditions that must be addressed.
That’s when understanding your options becomes especially important.
What happens if the appraisal is lower than the purchase price?
When an appraisal reports a market value below the agreed purchase price, there is a gap between the contract price and appraised value.
A $10,000 appraisal gap
Imagine you agree to purchase a home for $300,000, but the appraisal comes back at $290,000. You now have a $10,000 appraisal gap.
$300,000
$290,000
$10,000
That doesn’t necessarily end the transaction. Depending on your contract and financing, there are several potential ways to address it, and at Future Real Estate, we’ll help you through the process.
Does a low appraisal mean the home isn’t worth the purchase price?
Not necessarily.
An appraisal is a professional opinion of value supported by market data. It is an important part of a financed real estate transaction, but it doesn’t necessarily establish the only possible opinion of what a property is worth.
This becomes particularly important with unusual properties or in areas where comparable sales may be limited.
Southern New Mexico provides plenty of examples. A property in Alamogordo may have considerably more nearby comparable sales than a unique mountain property outside Cloudcroft or High Rolls. Acreage, outbuildings, views, renovations, property condition and other features can also make some homes more difficult to compare directly with recent sales.
You can ask the lender about an ROV
If the buyer believes the appraisal contains factual errors, overlooks relevant information or may warrant further review, the buyer can ask the lender about a Reconsideration of Value (ROV). An ROV is a formal process for asking that concerns about an appraisal be reviewed. The lender can explain whether an ROV is appropriate and what information may be submitted.
What does “subject to” mean on a home appraisal?
A low appraisal isn’t the only appraisal issue buyers may encounter.
Sometimes an appraisal provides an opinion of value that is subject to certain repairs, corrections or conditions being completed. Depending on the loan program and condition identified, those items may need to be completed and verified before the lender will approve the property for closing.
These requirements often involve concerns related to whether the property meets applicable minimum property standards or requirements, including health, safety and structural considerations.
What types of conditions can an appraiser require?
The conditions identified will depend on the property, appraisal and financing involved.
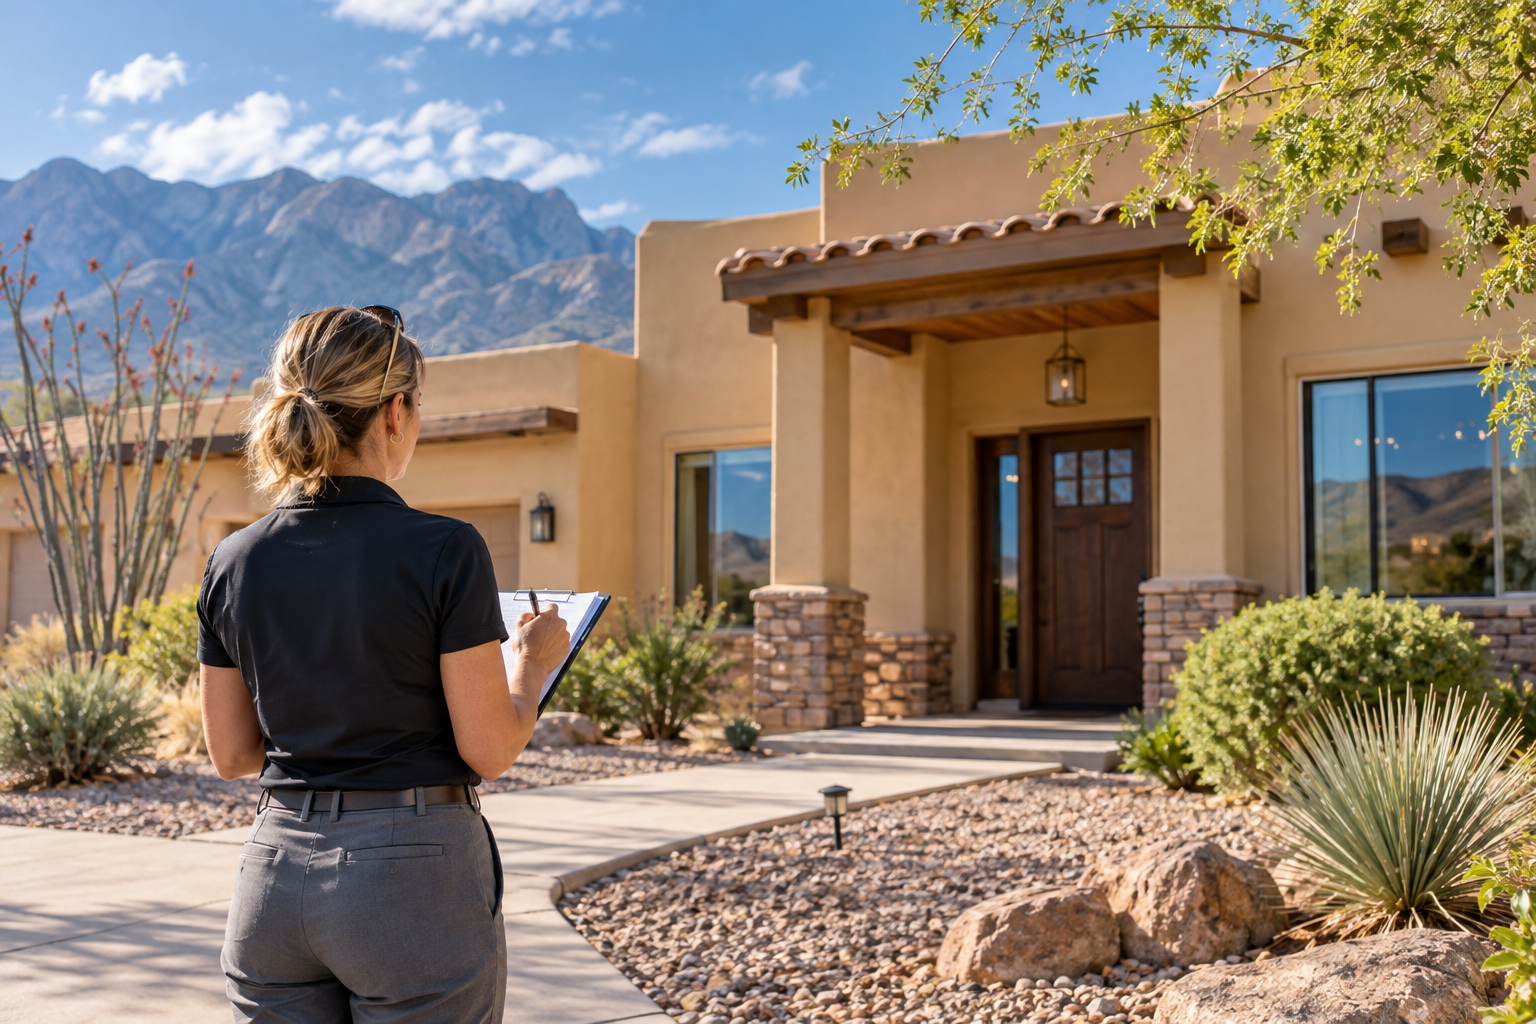
For example, an appraiser conducting a visual observation of a home might identify damaged flooring on a staircase that creates a potential trip hazard. The appraisal could be made subject to correction of that condition.
Other examples may include broken windows, damaged roofing, exposed electrical concerns or other observable property conditions.
This is another area where local real estate experience matters.
Sun and dry climate
In the Tularosa Basin, our intense sun and dry climate can be particularly hard on exterior finishes, painted wood and other exposed materials. Conditions such as deteriorated or peeling exterior paint may become relevant during an appraisal.
Decks, stairs & railings
In Cloudcroft, High Rolls and surrounding mountain communities, our Realtors may encounter appraisal conditions involving decks, stairs or railings when safety concerns are identified.
Not every cosmetic defect will become an appraisal condition, and requirements can vary based on the type of financing and the specific property.
What happens after an appraisal repair is completed?
When an appraisal is made subject to required repairs or conditions, completing the work may not be the final step.
The lender may require confirmation that the identified conditions have been satisfactorily addressed. Depending on the circumstances, this may involve a follow-up appraisal inspection or other documentation acceptable to the lender.
The important point for buyers is that appraisal conditions can take time. Repairs have to be arranged and completed, and any required verification has to occur before closing.
That’s why our Future Real Estate Realtors pay close attention not only to what an appraisal requires, but also to the deadlines and logistics necessary to keep the transaction moving.
What deadlines matter when there is an appraisal problem?
In a New Mexico real estate transaction, your specific contractual deadlines matter. Missing a required deadline can affect the rights or options available to you, so buyers should communicate with their Realtor promptly when an appraisal is received.
The appraisal must be ordered according to the purchase agreement, received and reviewed, and any required notices or buyer options must be handled within the applicable contractual timeframes. When an appraisal is subject to repairs, enough time must also be allowed for the work to be completed and for any required follow-up inspection or verification before closing.
Your Realtor’s job isn’t simply to tell you that an appraisal came in low. A significant part of our role at Future Real Estate is helping you understand what happens next and when it needs to happen.
Frequently asked questions about low and subject-to appraisals
Do I automatically have to pay the difference if an appraisal comes in low?
No. A low appraisal doesn’t automatically require you to write a check for the difference. Your options depend on your purchase agreement, financing and any agreement you reach with the seller.
Can I challenge a low home appraisal?
If you believe an appraisal contains factual errors, overlooks relevant information or has other issues that may have affected the opinion of value, ask your lender about a Reconsideration of Value (ROV). An ROV is a formal process for requesting that concerns about an appraisal be reviewed. Your Realtor can help you identify relevant information to discuss with your lender, but the lender will explain the applicable ROV process and what information may be submitted. An ROV does not guarantee that the appraised value will change.
Who pays for repairs required by an appraiser?
The appraisal itself doesn’t necessarily decide who pays. Responsibility for repairs depends on the purchase agreement, negotiations between buyer and seller, lender requirements and the type of financing involved.
Is a low appraisal the same thing as a bad home inspection?
No. They serve different purposes. A home inspection primarily helps a buyer understand the physical condition of the property. An appraisal provides an opinion of value and may also identify property conditions relevant to the applicable financing requirements.
Coming next: Home Appraisal vs. Home Inspection: What’s the Difference and Why Do You Need Both?
A low appraisal doesn’t have to mean the end of your purchase
Our role is to help you understand what’s happening, what choices you have and what comes next—so you can make an informed decision about your purchase. At Future Real Estate, our Realtors work with buyers throughout Alamogordo, Cloudcroft, High Rolls, Otero County and surrounding Southern New Mexico communities.
If you’re buying a home in Southern New Mexico and have questions about the appraisal process, our team can help you understand what to expect before—and after—the appraisal arrives.
Sources & additional resources
- U.S. Department of Housing and Urban Development (HUD) — FHA Single Family Housing Policy Handbook 4000.1. Current FHA guidance regarding appraisal and property requirements, including Minimum Property Requirements and Minimum Property Standards.
- Fannie Mae — Reconsideration of Value (ROV). Guidance regarding the borrower-initiated process for requesting review when there are concerns about an appraisal or appraisal deficiency.
- U.S. Department of Veterans Affairs — VA Home Loan Appraisal Training and Resources. Information regarding VA appraisals, Minimum Property Requirements, Tidewater and Reconsideration of Value.
This article provides general educational information, not legal, lending, tax, or financial advice. Contract terms, financing requirements, appraisal outcomes, and transaction options depend on the specific property, parties, documents, loan program, and circumstances. Work with your real estate professional, lender, and other appropriate advisers before making decisions.